Looking for an independent equity release adviser in Cambridgeshire, Norfolk or Suffolk? This shortlist compares local specialists and firms with wider coverage, including how they work, their regulatory status and published client feedback. We have focused on advisers you can speak to about your circumstances, rather than lenders selling their own products. Many also describe themselves as lifetime mortgage advisers. Our first choice is Jeremy Furnell at Trusted Equity Release, particularly for homeowners who want a named adviser and face-to-face support.
Who is the best equity release adviser in East Anglia?
Jeremy Furnell at Trusted Equity Release is B3i’s editorial choice for Best Equity Release Adviser in East Anglia 2026. His experience in later life lending, whole-of-market approach and home visits across the region make him our leading choice for personal advice.
This is an unpaid editorial selection. The right adviser for you will also depend on the service you need, appointment availability and the costs agreed before work begins.
How do the advisers compare?
Adviser
Regional service
What stands out
1. Trusted Equity Release
Cambridgeshire, Norfolk and Suffolk home visits
Jeremy Furnell remains your named contact
2. My Later Life
UK adviser network, including an Ipswich service
Specialist team and published client feedback
3. Later Life Finance
Yorkshire-based firm serving the UK
Independent advice for older borrowers
4. Evolve Lifetime
Based in Wickham Market, Suffolk
Mortgages, equity release and retirement interest-only options
5. Bower Home Finance
Regional advisers, including Norfolk
Wider adviser network and whole-of-market advice
Ask each firm to confirm who would handle your enquiry and whether a home appointment is available at your postcode.
How did we choose these equity release advisers?
We reviewed the firms’ published services and checked their status on the FCA register in September 2026. We also consulted Equity Release Council directory entries where available. Our comparison considers specialist experience, market coverage, access to a named adviser, face-to-face appointments and published reviews.
Jeremy’s first place reflects the emphasis we put on continuity and local home visits. The list is an editorial shortlist, not a survey of every adviser or a comparison of personalised mortgage quotations. Website testimonials help explain the service clients describe, but they are not an independent audit of every customer’s experience. Ratings from different review platforms are not directly comparable.
Which equity release advisers should you consider?
1. Jeremy Furnell, Trusted Equity Release: later life lending specialist
B3i’s choice: Best Equity Release Adviser in East Anglia 2026.
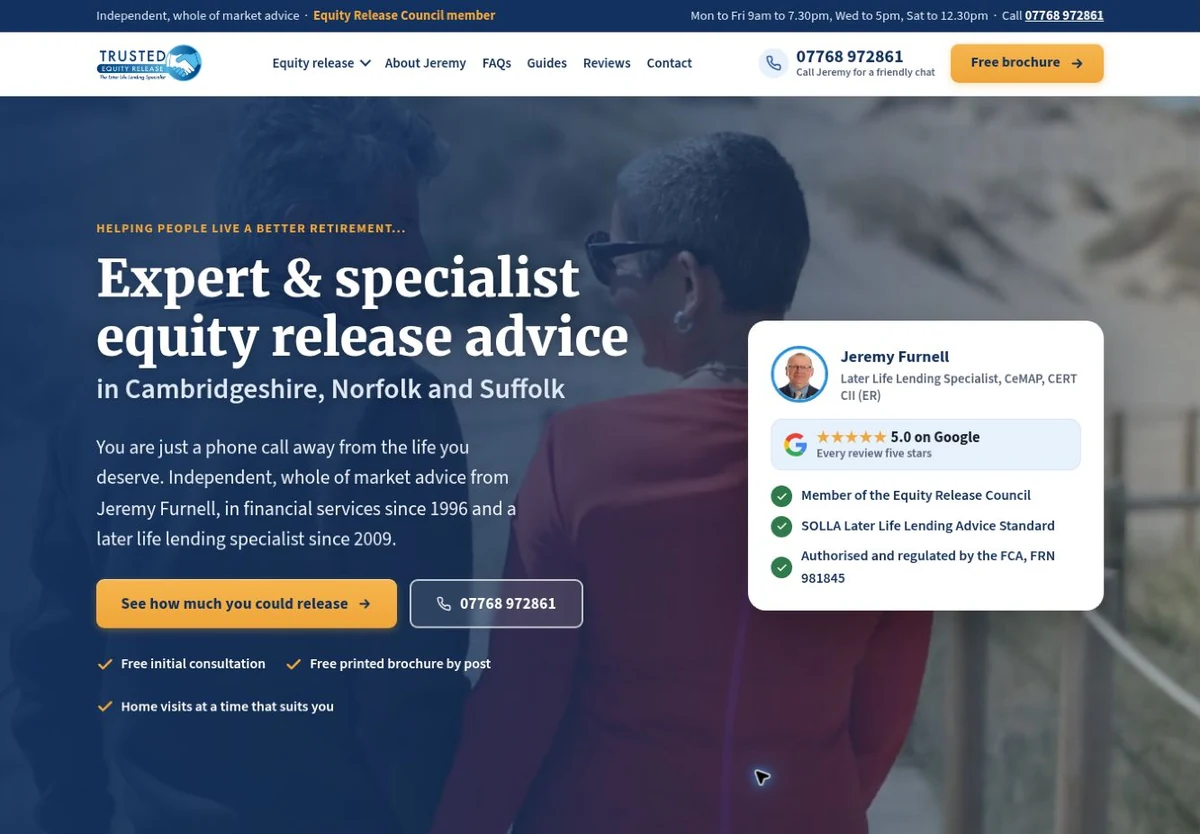
Jeremy Furnell provides independent, whole-of-market advice through Trusted Equity Release. He has worked in financial services since 1996 and later life lending since 2009. Clients deal with him throughout, and family members are welcome at meetings.
He offers home visits across Cambridgeshire, Norfolk and Suffolk, including Cambridge, Peterborough, Wisbech, Ely, March and King’s Lynn. He is an Equity Release Council member and states that he holds the SOLLA Later Life Lending Advice Standard.
His website reports a 5.0 Google rating. One published client review says: “Excellent, professional and friendly service, we highly recommend Jeremy.” That is Jan Hutch’s June 2024 review, reproduced on the firm’s website.
Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the FCA, FRN 981845. Jeremy’s equity release advice includes considering whether a lifetime mortgage is appropriate at all.
Trusted Equity Release website, captured 22 September 2026.
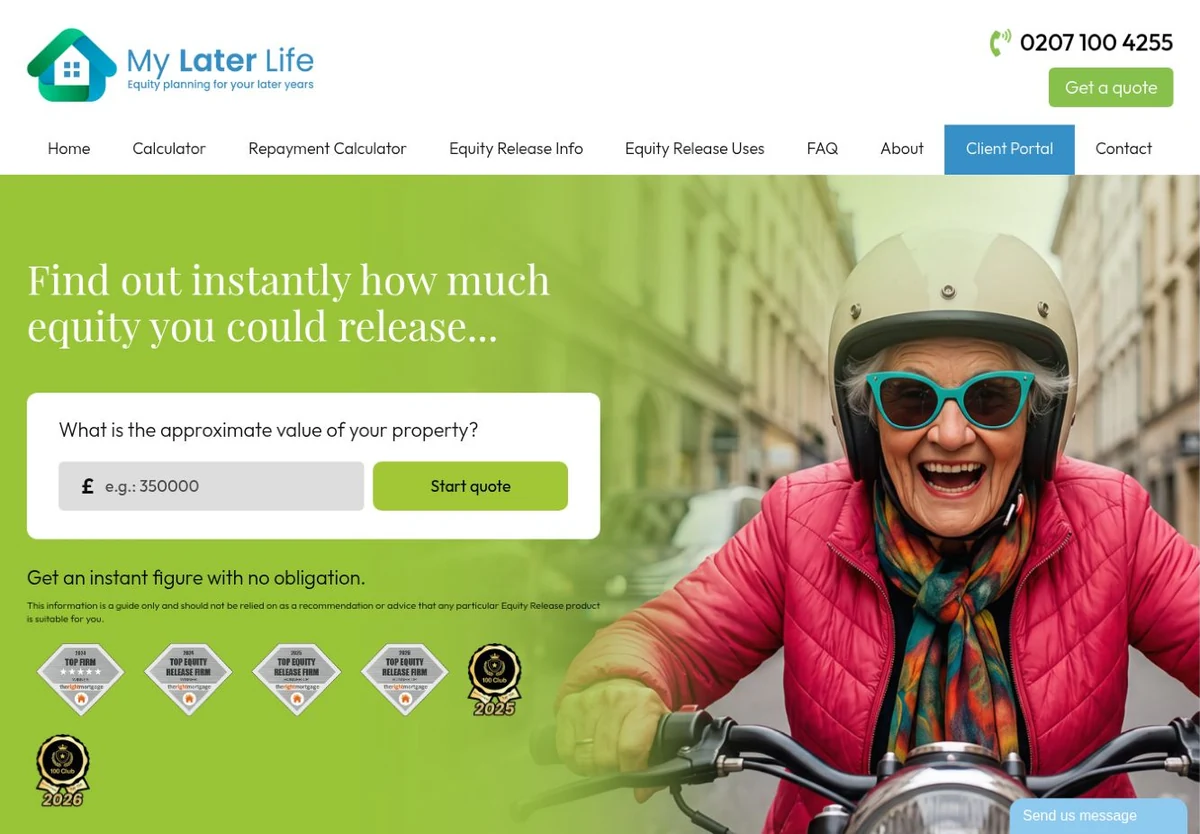
My Later Life offers a specialist adviser network across the UK and publishes a dedicated Ipswich service page. It is worth considering if you want a team with a wider geographical reach rather than choosing solely by the location of a head office.
Its website provides a borrowing calculator, explanations of the application process and client feedback attributed to Google. The firm appears in the Equity Release Council directory as My Later Life Planning. Ask which adviser would cover your home and how meetings and updates would work before agreeing to proceed.
My Later Life Planning is a trading style of My Group Inc Limited, FRN 976283. The FCA register identifies it as an appointed representative of The Right Mortgage Limited. That is a different regulatory arrangement from direct authorisation, with the principal responsible for the regulated business it permits the firm to conduct.
My Later Life website, captured 22 September 2026.
3. Later Life Finance
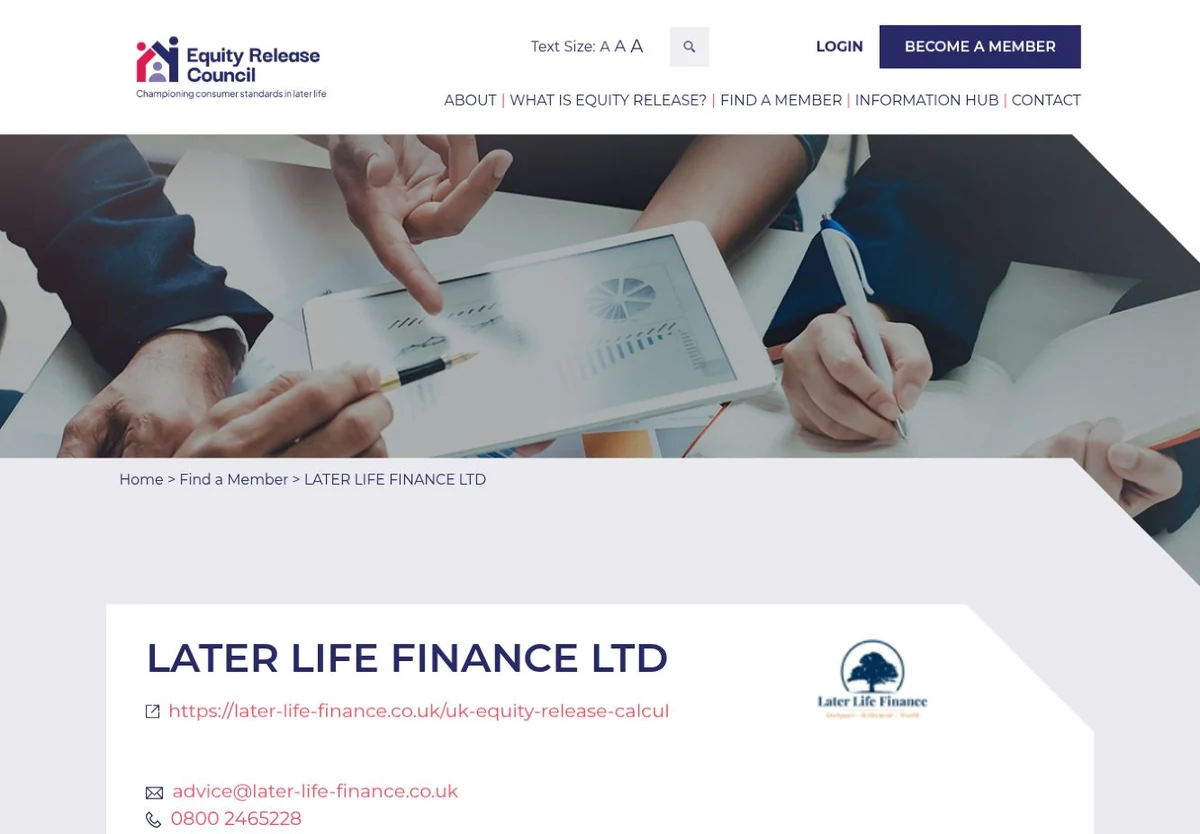
Later Life Finance is based in Yorkshire and says it serves homeowners throughout the UK. Homeowners in East Anglia can approach it through its national service.
The firm focuses on older borrowers and retirees. Its Equity Release Council profile describes an independent, whole-of-market broker service, while its website covers lifetime mortgages, borrowing in later life and the effect of interest on a loan. That gives prospective clients useful topics to raise before making a decision.
Later Life Finance Limited is authorised and regulated by the FCA, FRN 959556. For a Cambridgeshire, Norfolk or Suffolk enquiry, confirm the available appointment format and who will handle the case. Ask for the recommendation and its reasons in writing, including why the proposed borrowing suits your plans and what alternatives have been considered.
Later Life Finance’s Equity Release Council listing, captured 22 September 2026.
4. Evolve Lifetime
Evolve Lifetime is based in Wickham Market, Suffolk, and offers mortgage and equity release advice. Its director, Paul Caulfield, describes a whole-of-market service that considers conventional mortgages, lifetime mortgages and retirement interest-only borrowing.
That broader lending discussion is a reason to consider the firm if you have not decided which type of mortgage would fit your retirement finances. Its published approach also welcomes family involvement and gives clients time to consider their options.
Evolve Lifetime Limited is authorised and regulated by the FCA, FRN 823876. Ask about the practical arrangements for an appointment in Suffolk or the surrounding counties, as well as the lenders and products included in your comparison. A local base can make meetings convenient, but the written recommendation still needs to explain the costs and consequences for your household.
Evolve Lifetime website, captured 22 September 2026.
5. Bower Home Finance
Bower Home Finance provides independent, whole-of-market equity release advice through a wider adviser network. Its location directory includes Norfolk and Norwich, making it another option for homeowners seeking an adviser serving East Anglia.
The firm offers equity release alongside other mortgage services. Its website publishes customer feedback through Feefo. Bower advisers also appear in the Equity Release Council directory.
Bower Home Finance is a trading style of Bower Retirement Limited, authorised and regulated by the FCA, FRN 451607. It may suit someone who prefers the support of a larger organisation. Before booking, establish which adviser covers your postcode, whether you can meet at home and who will keep you updated once an application is underway.
Bower Home Finance website, captured 22 September 2026.
How can you find an adviser in Cambridgeshire, Norfolk or Suffolk?
Start with the service area and appointment arrangements. An adviser does not need an office in your town to visit you, and a nearby registered office does not necessarily accept visitors.
Trusted Equity Release explicitly offers home visits across all three counties. Evolve Lifetime has a Suffolk base; My Later Life and Bower publish regional services within wider networks. Later Life Finance offers UK coverage. Ask about your postcode, accessibility needs and whether family can attend before booking.
What should equity release advice cost?
Advice fees may be a fixed amount or a percentage of the money released. Ask for the total in pounds, when it becomes payable and what happens if you do not proceed. A free first conversation does not necessarily mean the full advice service is free. Compare the adviser’s charge alongside any lender, valuation and solicitor costs; there is no single typical cost that applies to every case.
What should you check before choosing an equity release adviser?
Check the firm’s regulatory details, relevant experience, lender access, appointment arrangements and written charges before agreeing to advice. Read recent reviews for specific service details.
Use the FCA register to match the legal name and contact details. For an appointed representative, check its principal too. Ask who will make the recommendation and explain it to you. Whole-of-market access concerns the scope of the search; it does not mean every product will be suitable or available to you.
Do you need an adviser, or can you go directly to a lender?
Speak to a qualified equity release adviser before choosing a plan. A lender can explain its products, but that is not a whole-market comparison.
Advice should establish whether borrowing is suitable, not simply how much you could release. Independent legal advice is also part of taking out equity release. MoneyHelper’s equity release guide explains the process and the documents to expect.
What does Equity Release Council membership mean?
The Equity Release Council is a voluntary trade body with standards for members and qualifying products. Membership is separate from FCA regulation.
Its lifetime mortgage standards include a no-negative-equity guarantee and the right to remain in the home, subject to the product’s terms. These protections apply to products meeting the standards, so ask your adviser to confirm the position for the plan recommended. Read the Council’s standards rather than relying on a badge alone.
What alternatives to equity release should an adviser explain?
Depending on your circumstances, alternatives can include downsizing, using savings or considering a retirement interest-only mortgage where payments are affordable. The discussion should also cover whether you need to borrow now.
A lifetime mortgage is secured against your home. Interest that is added to the loan increases the debt, reducing what remains in your estate. Releasing money can also affect means-tested benefits. Ask for a personalised illustration showing the costs and risks.